Written by Monica Izu, founder of WeFixPay · Figures checked against HMRC, GOV.UK and NHS Employers · Last reviewed: 17 November 2026
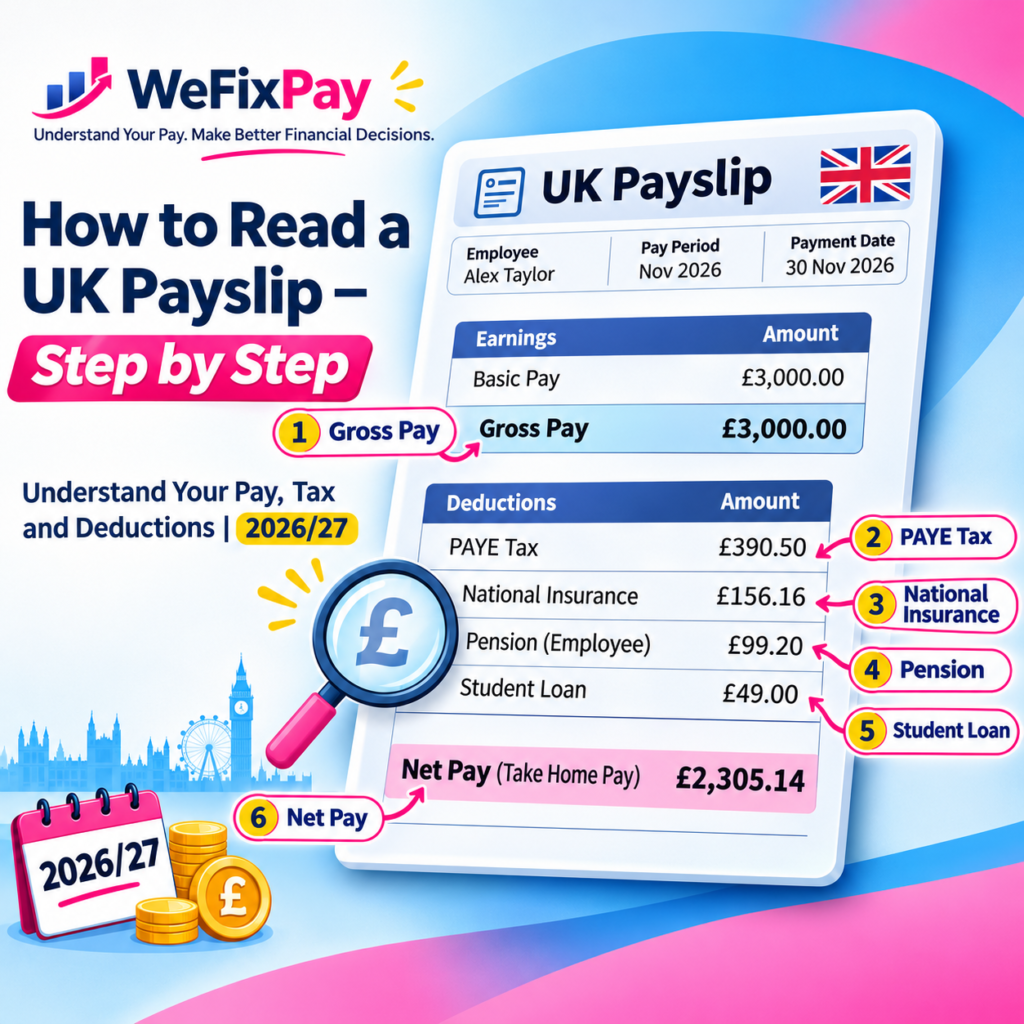
UK tax year 2026/27 · 6 April 2026 to 5 April 2027
Learning how to read a UK payslip makes it easier to check whether you have been paid correctly. This step-by-step guide shows where to find gross pay, PAYE Income Tax, National Insurance, pension deductions, student loan repayments and your final take-home pay.
We'll follow an illustrative £36,000-a-year employee through a sample monthly payslip, then explain the entries that often confuse workers, including NHS employees. You can compare your own figures using the free WeFixPay Payslip Checker.
What should a UK payslip show?
Employers must generally provide workers with a payslip on or before payday. It must show gross earnings, pay deductions and net wages. Where pay varies by time worked, it must also show the relevant hours. Tax code, NI number, year-to-date figures and other details may be included depending on the employer. See GOV.UK's payslip requirements.
Annotated example: a UK monthly payslip
Imagine an employee in England earning £36,000 annually (£3,000 per month), paid monthly with tax code 1257L, NI category A, a Plan 2 student loan and a standard qualifying-earnings workplace pension using relief at source. There are no bonuses, taxable benefits, other deductions or earlier payroll adjustments. The worked PAYE example assumes a normal month with the standard allowance available.
| Item on payslip | What it tells you | Amount |
|---|---|---|
| 1Basic salary | Gross earnings for the month | £3,000.00 |
| 2Tax code: 1257L | Standard allowance code for this example | — |
| 3PAYE Income Tax | Illustrative 20% tax on £1,952.50 monthly taxable pay | −£390.50 |
| 4National Insurance (A) | 8% on monthly pay above £1,048 | −£156.16 |
| 5Employee pension | Relief-at-source deduction: 4% of £2,480 qualifying pay | −£99.20 |
| 6Student Loan Plan 2 | 9% above £2,448.75, rounded down to whole pounds | −£49.00 |
| 7NET PAY | The amount received after deductions | £2,305.14 |
Also shown on many real payslips: payroll number, pay date, NI letter, pay period, hours, taxable pay, pension scheme information, and year-to-date pay/tax totals. Employer pension contributions are normally additional to the employee's take-home-pay calculation.
Check the arithmetic: £3,000.00 − £390.50 − £156.16 − £99.20 − £49.00 = £2,305.14 net pay. This example does not imply that everyone on £36,000 will take home the same amount.
How each payslip deduction was calculated
1. Gross earnings: £3,000
The monthly gross salary is £36,000 ÷ 12. Your own gross pay may also include shifts, overtime, enhancements, commission, bonuses or allowances. Compare the recorded hours and rates with your contract and rota before checking tax.
2. PAYE Income Tax: £390.50
For an illustrative England employee with the standard £12,570 Personal Allowance and all employment earnings taxed at the 20% basic rate, annual taxable income is £36,000 − £12,570 = £23,430. Annual Income Tax is £4,686, equal to £390.50 per month for a simple, even-pay comparison. Actual cumulative PAYE calculations can differ by pay period, prior employment, taxable benefits or tax-code changes. Scotland has different Income Tax bands for employment earnings.
Use the UK Tax Calculator or read our UK Tax Codes Explained guide if your code is not 1257L.
3. Employee National Insurance: £156.16
For category A, the main employee NI rate in 2026/27 is 8% between the monthly primary threshold of £1,048 and upper earnings limit of £4,189, with 2% above that limit. At £3,000 monthly pay, the illustrated NI deduction is (£3,000 − £1,048) × 8% = £156.16. NI uses pay-period rules rather than the same cumulative method as PAYE. Estimate your NI.
4. Workplace pension: £99.20 taken from take-home pay
For this example, qualifying earnings are £3,000 − £520 = £2,480 per month. The conventional automatic-enrolment minimum employee-side gross contribution is 5% of qualifying earnings: £124.00. Under a relief-at-source arrangement, the employee pays 80% of that amount (£99.20) and the pension provider claims the other £24.80 in basic-rate tax relief. A typical 3% employer contribution adds a further £74.40 to the pension arrangement; it is not a deduction from the worker's £3,000 pay.
5. Plan 2 student loan: £49
The 2026/27 Plan 2 threshold is £29,385 per year, or £2,448.75 per month. The calculation is (£3,000 − £2,448.75) × 9% = £49.6125. HMRC's payroll rule rounds the deduction down to the nearest whole pound, so £49 is shown on the example payslip. Other plans have different thresholds; Postgraduate Loan repayment is calculated separately. Check your student loan deductions.
How to read your tax code, NI letter and YTD totals
| Field | What to check |
|---|---|
| Tax code | 1257L is common when the standard Personal Allowance applies. BR, 0T, K and emergency suffixes such as W1/M1 can alter the PAYE amount. Scotland codes commonly begin with S. |
| NI category | A is common, but other letters can change how NI is calculated. Confirm the correct category applies to you. |
| Taxable pay YTD | Pay subject to Income Tax since 6 April. It can differ from gross pay where tax treatment is different. |
| Tax paid YTD | Total PAYE withheld so far in the tax year; useful when checking refunds or a change of job. |
| NI YTD | Accumulated NI deductions, where the employer provides this information. |
| Pay period and pay date | Check whether earnings relate to calendar months, four-weekly pay, or another payroll cycle. |
Important distinction: Some payroll deductions change each period, while others are fixed. Look for court orders, union subscriptions, salary advances, season-ticket loans or other contractual deductions where applicable. A payslip discrepancy does not by itself prove a payroll error.
How to read an NHS payslip
NHS payslips can be more detailed because your total pay may be made up of basic salary plus unsocial-hours enhancements, overtime, on-call or other allowances. The names of lines vary by NHS employer, payroll software and nation. Do not assume that every employer uses the same abbreviations.
| Common type of line | What to check |
|---|---|
| Basic pay | Your contracted hours, band/grade and pay point for the period |
| Enhancements / unsocial hours | Relevant eligible hours, rates and when those shifts were processed |
| Overtime / bank shifts | Whether the shifts appear in this payroll period or a later one |
| NHS pension | Your employee contribution and whether the employer used the correct pensionable pay |
| PAYE / NI / student loan | Statutory deductions, which may vary when enhancements increase gross earnings |
| Year-to-date totals | Useful for investigating recurring differences across payslips |
NHS pensions are not the same as the simple 5% workplace pension illustrated earlier. NHS pension contribution structures depend on the applicable NHS pension scheme and pay tier; Scottish and other UK arrangements can differ. For NHS-specific figures, compare your payslip with your employer's official payroll guidance and pension scheme information.
Seven checks to make before contacting payroll
- Confirm the correct employee name, employer, payroll number and pay period.
- Match basic salary, paid hours, overtime and enhancements against your contract and rota.
- Check the tax code and whether you had a second job, new job or recent code change.
- Identify your NI category and any unusual NI deductions.
- Confirm your pension contribution rate and whether the scheme uses net pay, relief at source or salary sacrifice.
- Check student loan plan, current pay-period threshold and any postgraduate loan.
- Reconcile gross earnings minus the listed deductions against the net pay and bank deposit.
If something still looks wrong, contact your payroll or HR team with the relevant pay period and specific line items, rather than uploading your unredacted payslip to public forums. For questions about the tax code recorded by HMRC, check your personal tax account. Keep a copy of your contract, rota and payslips.
- Payslip Checker — review the figures on your payslip and highlight possible differences.
- Salary Calculator — compare estimated take-home pay using your assumptions.
- UK Tax Calculator and NI Calculator — investigate individual deductions.
- Why is my take-home pay lower than expected? — eight practical causes of differences.
Frequently asked questions
Why is my net pay lower than my gross pay?
Gross pay is before deductions. Net pay is the amount after Income Tax, employee National Insurance, pension deductions, student loans and any other applicable deductions. The exact difference depends on your circumstances and pay period.
Why is my tax higher this month?
A bonus, overtime, changed tax code, emergency code, prior pay adjustment or taxable benefit can all affect PAYE. Check the tax code, taxable pay and tax paid YTD before assuming there is an error.
Why doesn't my student loan payment match 9% of my whole salary?
For Plans 1, 2, 4 and 5, 9% is applied to relevant earnings above the applicable pay-period threshold, not to all earnings. HMRC rounds a calculated deduction down to whole pounds. Postgraduate loans use a different 6% rate.
Do I pay National Insurance differently in Scotland?
Standard employee Class 1 NI rates and thresholds are generally UK-wide. Scottish employment Income Tax bands differ from those in England, Wales and Northern Ireland.
Why is my NHS payslip different after working a night shift?
Unsocial-hours enhancements and overtime can raise your gross pay and change deductions. Some earnings may also appear in a later pay period because of a payroll cut-off. Check the dates of eligible shifts and the employer's payroll timetable.
Does my employer's pension contribution reduce my net pay?
Ordinarily, employer contributions are paid on top of employee pay, not deducted from it. Employee contributions may reduce net pay, depending on how the pension scheme operates.
Can I use a calculator to prove my payslip is wrong?
A calculator can help identify a potential mismatch, but it cannot account for every employer-specific payroll rule or personal tax circumstance. Check the relevant records and ask payroll for an explanation before concluding an error was made.
Official sources and further reading
The worked example uses public 2026/27 thresholds and rates. These official resources should be rechecked when the tax year changes.
- GOV.UK — Payslip requirements
- HMRC — Rates and thresholds for employers, 2026/27
- GOV.UK — Employee National Insurance rates
- HMRC — 2026/27 student loan deduction tables and rounding
- The Pensions Regulator — 2026/27 qualifying earnings thresholds
- GOV.UK — Net pay and relief-at-source workplace pensions
Last reviewed: 15 November 2026. Educational guidance only; individual payroll results may differ.